The Ultimate Guide to Business Valuation Before Mergers, Acquisitions or Fundraising
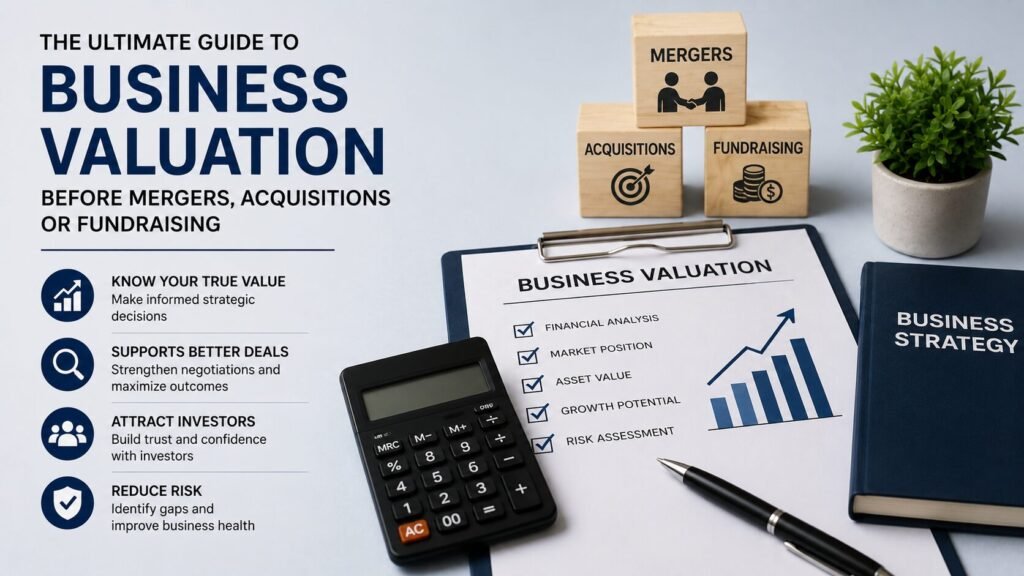
TL;DR Business Valuation helps determine the economic worth of a company before mergers, acquisitions, fundraising, investor negotiations, ESOP planning, restructuring, or strategic exits. A reliable valuation is not based on guesswork. It requires clean financial statements, realistic projections, industry benchmarking, tax review, asset assessment, cash-flow analysis, risk evaluation, and professional judgement. For founders and business owners, valuation is not only about getting a higher number. It is about defending that number during negotiation and due diligence. Why Business Valuation Matters Before Major Transactions Business owners often think about valuation only when an investor asks, a buyer appears, or a merger discussion begins. By then, the business may not be valuation-ready. A rushed valuation can create problems. The business may have: Unclear financial records Weak MIS reports Poor cash-flow visibility Unreconciled GST or tax records Informal related-party transactions Unrecorded assets or liabilities Over-optimistic projections Customer concentration risk Unclear ownership structure Pending compliance issues These gaps can reduce valuation, delay transactions, or weaken negotiation power. A professional Business Valuation helps owners understand what the business is worth, what drives that value, and what must be improved before approaching investors, buyers, or strategic partners. What Is Business Valuation? Business Valuation is the process of estimating the fair economic value of a business using recognised financial methods, market benchmarks, asset values, cash flows, earnings, growth potential, and risk factors. It may be used for: Fundraising Mergers Acquisitions Business sale Partner exit Family settlement ESOP planning Dispute resolution Restructuring Bank finance Strategic planning Investor due diligence A valuation report should not simply present a number. It should explain the logic behind the number. A strong valuation answers: What is the business worth today? What assumptions support this value? What risks may reduce value? What factors can improve valuation before a transaction? When Does a Business Need Valuation? A business may need valuation in several situations. 1. Before Fundraising Startups and growing companies need valuation before issuing shares to investors. This helps founders negotiate: Pre-money valuation Post-money valuation Equity dilution Investor rights ESOP pool Convertible instruments Future funding rounds 2. Before Merger or Acquisition Buyers and sellers need valuation to understand fair deal value. In M&A, valuation helps determine: Purchase price Share swap ratio Earn-out terms Control premium Synergy value Exit consideration 3. Before Selling a Business A business owner planning an exit needs a defensible valuation before entering buyer discussions. 4. For ESOP Planning Startups and companies issuing employee stock options may need valuation support for fair pricing and compliance. 5. For Partner or Shareholder Exit When a partner or shareholder exits, valuation helps determine fair settlement value. 6. For Family Business Succession Family-owned businesses need valuation for ownership transfer, restructuring, settlement, and wealth planning. Common Business Valuation Methods There is no single valuation method suitable for every business. The right method depends on business stage, industry, profitability, asset base, growth rate, transaction purpose, and data quality. Common methods include DCF, comparable company analysis, precedent transaction method, asset-based valuation, and revenue or EBITDA multiples. 1. Discounted Cash Flow Method The Discounted Cash Flow method estimates business value based on expected future cash flows discounted to present value. It is widely used where the business has predictable financial projections. Best Suited For Mature businesses Profitable SMEs Manufacturing companies Service businesses with stable contracts Companies with reliable forecasts Businesses preparing for M&A or funding Key Inputs Revenue projections EBITDA margins Working capital needs Capital expenditure Tax rate Discount rate Terminal value Growth assumptions Practical Risk DCF is highly sensitive to assumptions. A small change in growth rate, margin, discount rate, or terminal value can materially change valuation. That is why projections must be realistic and supportable. 2. Comparable Company Method This method values a business by comparing it with similar listed or private companies. Common multiples include: EV/Revenue EV/EBITDA P/E ratio Price-to-sales Sector-specific multiples Best Suited For Businesses in sectors with available benchmarks Startups with comparable funded peers M&A negotiations Strategic exits Investor pitch valuation support Practical Risk No two companies are exactly the same. Differences in scale, profitability, growth, governance, margins, geography, and customer quality must be adjusted. 3. Precedent Transaction Method This method uses valuation multiples from past transactions involving similar businesses. It is especially useful in M&A. Best Suited For Business sale Strategic acquisition Sector consolidation Buyer-seller negotiations Private equity discussions Practical Risk Many private transaction details are not publicly available. Headline deal value may not reveal earn-outs, debt adjustments, working capital adjustments, or non-cash consideration. 4. Asset-Based Valuation This method values a business based on assets minus liabilities. It may include: Fixed assets Land and buildings Machinery Investments Inventory Receivables Loans Liabilities Best Suited For Asset-heavy businesses Real estate holding companies Manufacturing units Distressed businesses Liquidation scenarios Family settlements Practical Risk Asset-based valuation may undervalue businesses with strong brands, customer relationships, technology, or future earning potential. 5. Revenue and EBITDA Multiples Many businesses are valued using revenue or EBITDA multiples. Revenue Multiple Commonly used for high-growth startups or companies where profits are not yet stable. EBITDA Multiple Commonly used for profitable SMEs and mature businesses. Best Suited For SaaS businesses D2C brands Agencies Service businesses Profitable SMEs Growth companies Practical Risk Multiples must be selected carefully. A business with ₹10 crore revenue and weak margins may not deserve the same multiple as a business with ₹10 crore revenue and strong recurring revenue. 6. Startup-Specific Valuation Methods Early-stage startups often do not have stable profits. In such cases, valuation may consider: Market opportunity Founder quality Product stage Revenue traction User growth Technology moat Comparable funding rounds Unit economics Burn rate Runway Investor demand Common startup valuation methods may include scorecard, VC method, Berkus method, comparable funding benchmarks, and DCF for revenue-stage startups. Recent India-focused startup valuation guides discuss DCF, comparable analysis, VC method, Berkus, and other startup-specific methods. Key Factors That Influence Business Valuation 1. Revenue Quality Investors and buyers prefer recurring, predictable, diversified revenue. Higher valuation is likely when revenue is: Recurring Contracted Growing Diversified Collection-backed Low-churn High-margin 2. Profitability Profit matters,