Family Business Succession Planning: Tax, Legal and Wealth Management Considerations
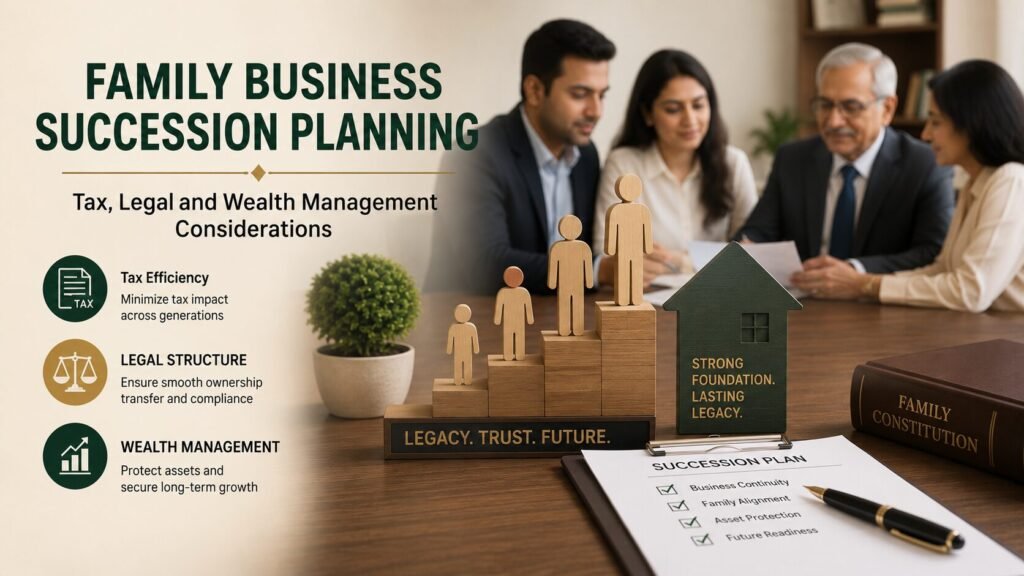
TL;DR Family Business Succession Planning is the process of transferring ownership, control, management responsibility, and wealth from one generation to the next without disrupting the business. A good succession plan should cover tax impact, legal documentation, ownership rights, management roles, family governance, wealth protection, asset transfer, estate planning, and dispute prevention. For Indian family businesses, succession planning should not begin after a crisis. It should begin while the current generation is active, capable, and able to guide the transition. Why Succession Planning Matters for Family Businesses Family businesses are built on trust, relationships, reputation, and years of effort. But without proper succession planning, even profitable businesses can face disputes, uncertainty, tax issues, and operational disruption. Many family businesses delay succession planning because the topic feels sensitive. Owners may assume that the next generation will naturally take over or that family members will resolve matters internally when the time comes. In practice, unclear succession often creates problems such as: Disputes between family members Unclear ownership rights Confusion over management control Tax exposure during asset transfer Delayed decision-making Business valuation disputes Family wealth fragmentation Legal challenges after the founder’s death Conflict between active and non-active family members Loss of business continuity Succession planning is not only about inheritance. It is about continuity. A strong plan protects the family, the business, employees, creditors, customers, and future generations. What Is Family Business Succession Planning? Family Business Succession Planning is a structured process through which a family decides how business ownership, control, wealth, responsibilities, and decision-making will pass from one generation to another. It generally includes: Ownership transfer Management transition Tax planning Legal documentation Family wealth protection Governance rules Role clarity Business continuity planning Dispute prevention Estate planning Asset allocation Retirement planning for senior generation The goal is to ensure that business value does not get destroyed during transition. A good succession plan answers three important questions: Who will own the business? Who will manage the business? How will wealth and control be protected fairly? Ownership Succession vs Management Succession One of the biggest mistakes family businesses make is assuming that ownership and management are the same. They are different. Ownership Succession Ownership succession decides who will hold shares, partnership interest, business assets, voting rights, economic rights, and family wealth. This may involve: Shares Partnership rights LLP contribution Business assets Immovable property Investments Family trusts Wills Gift deeds Family settlement agreements Management Succession Management succession decides who will run the business. This includes: Managing director role Board participation Operational leadership Finance control Signing authority Strategic decision-making Professional management involvement Role of next-generation family members A family member may own part of the business but may not be involved in management. Clear separation prevents conflict. Key Tax Considerations in Family Business Succession Planning Tax planning is one of the most important parts of succession. Poorly planned transfers can create unnecessary tax liability, cash-flow pressure, stamp duty exposure, compliance issues, and disputes. 1. Capital Gains Impact Transfer of shares, property, business assets, or ownership rights may trigger capital gains tax depending on the mode of transfer. Families should review: Nature of asset Holding period Cost of acquisition Fair market value Transfer method Exemptions available Tax reporting requirements Example If business property is transferred without proper planning, the family may face capital gains and stamp duty implications. A professional review helps identify the most tax-efficient route. 2. Gift and Family Transfer Planning Gifts between specified relatives may receive favourable tax treatment under certain conditions. However, documentation is still important. Families should not treat informal transfers casually. Proper documentation may include: Gift deed Board approval Share transfer forms Valuation report Family settlement agreement Bank trail Accounting entries Tax disclosure Even when a transfer is exempt, documentation protects the family during future tax review or dispute. 3. Stamp Duty and Documentation Asset transfers may attract stamp duty depending on the asset type and state law. This is especially relevant for: Immovable property Share transfers Partnership reconstitution Business restructuring Family settlements Trust deeds Gift deeds Before executing any succession document, stamp duty and registration requirements should be evaluated. 4. Trust Taxation Private family trusts are increasingly used for wealth protection and succession planning. However, taxation depends on the type of trust. Common trust structures include: Specific trust Discretionary trust Revocable trust Irrevocable trust Tax treatment may differ based on whether beneficiaries are identifiable, whether shares are determinate, and whether the trust earns business income. A trust should not be created only for control. It must be designed carefully from tax, legal, governance, and family perspectives. 5. Business Restructuring Sometimes succession requires restructuring before transfer. This may include: Converting proprietorship into LLP or company Separating business assets from personal assets Creating holding company structures Demerging different business verticals Separating real estate from operating business Issuing shares to family members Reorganising partnership rights Creating family investment entities Restructuring should be done before succession pressure arises. Last-minute restructuring can create tax and compliance complications. Key Legal Considerations Succession planning must be legally enforceable. Verbal understanding within the family is not enough. 1. Wills A will is one of the most basic estate planning documents. It helps define how assets should pass after the owner’s death. A will may cover: Shares Bank accounts Immovable property Investments Personal assets Business interests Family heirlooms However, a will may not always be enough for complex family businesses. It may not address management control, business continuity, voting rights, or active vs non-active family members. 2. Family Settlement Agreement A family settlement agreement records how family members agree to distribute assets, rights, responsibilities, and claims. It is useful when: Multiple heirs are involved Business branches need separation Ownership needs clarity Disputes need prevention Active and passive members need defined rights Family assets need division A well-drafted family settlement can reduce future litigation. 3. Private Family Trusts A private family trust can help manage family wealth and business interests across generations. It may help with: Asset protection Continuity of ownership Wealth preservation Controlled distribution Protection for minors Governance